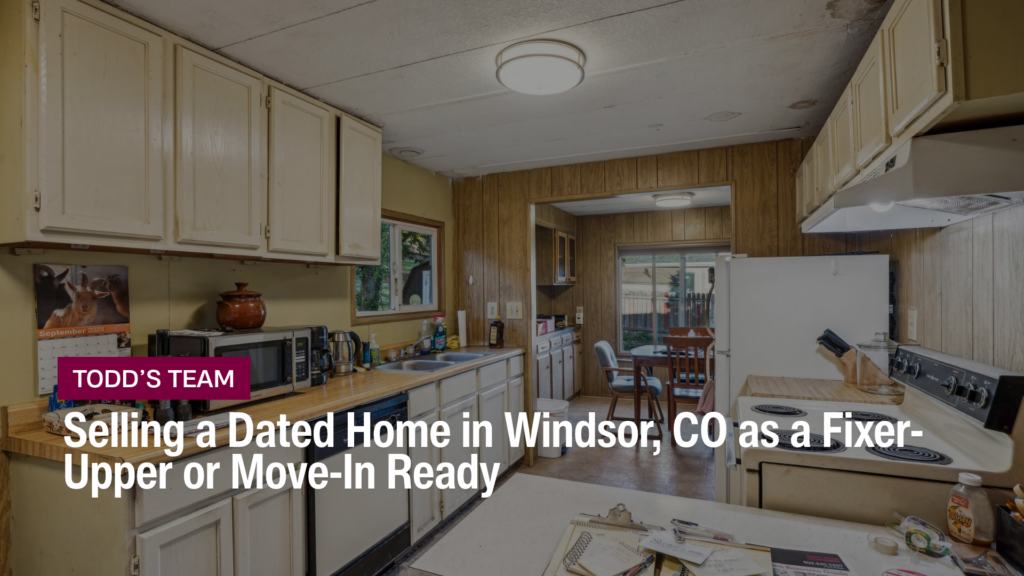
Selling a dated home in Windsor, CO as a fixer-upper or move-in ready is usually a false choice. You have three paths: market it honestly as original condition and price it against other original homes, label it a fixer-upper for investors, or update it to compete with move-in ready listings. For a well-kept house that is dated but working, the first path often nets the most.
Many established Windsor neighborhoods have 1980s and 1990s homes with original kitchens, carpet, and baths. Nothing is broken. It just looks its age. The label you choose decides which buyers show up and which sales they compare your home against.
Dated Is Not the Same as a Fixer-Upper
Appraisers draw this line clearly. The condition rating definitions Fannie Mae and Freddie Mac publish for appraisers treat a kitchen or bath that is dated but fully functional as typical of an adequately maintained home. Worn roofing, damaged cabinets, and missing floor coverings are what push a rating toward repair territory.
Call an original but sound house a fixer-upper, and buyers price it like the second group.
| Listing Label | Buyers It Attracts | How They Price It | Main Risk |
|---|---|---|---|
| Fixer-upper or investor special | Flippers, cash investors | Resale value minus repairs and profit | Offers below what condition justifies |
| Original condition, well kept | Renovators, renovation-loan buyers, some investors | Against original-condition sales | Needs honest photos and remarks |
| Move-in ready | Broadest financed buyer pool | Against updated sales | Dated finishes read as overpriced |
Who Actually Buys an Original House
Buyers notice a 1980s kitchen in the first photo. What they care about, and what they will pay for, depends on which of these groups they belong to:
- Renovators want to pick their own finishes. They care about layout, lot, and systems, not finishes they will tear out.
- Investors work backward from resale value. They often pay cash and close quickly, but their margin comes out of your price.
- Renovation-loan buyers use programs like the FHA 203(k) rehabilitation mortgage or Fannie Mae HomeStyle to finance the purchase and the remodel in one loan. They can pay closer to full value, though closings often take longer.
A fixer-upper label speaks mainly to investors. An honest original-condition label keeps all three groups in play.
Pricing Comps When Selling a Dated Home in Windsor
The most common mistake is pricing an original home off the updated sale down the street. Buyers and appraisers see the difference, and the listing sits. Todd starts with sales that match your home’s age, size, and condition, using the same sources for sold home prices in Windsor that buyers’ agents use.
| Comparable Sale | What It Tells You | How Todd Uses It |
|---|---|---|
| Original-condition sale, same era | Closest indicator of value | Anchors the list price |
| Updated sale nearby | Ceiling, not target | Shows the discount buyers apply |
| Recent flip resale | After-repair value | Predicts investor offers |
| Active dated listing | Current competition | Positions your price and photos |
Before recommending a label, Todd works through these steps:
- Separate finish issues from function issues like the roof, furnace, and water heater.
- Pull original-condition and updated sales from the same era of homes.
- Compare the price gap with what updating would actually cost.
- Write MLS public remarks that match the label and name what is solid.
- Set a round-number price so the home appears in more search ranges.
Should You Update Anything First?
Sometimes a little. A deep clean, fresh neutral paint in the main rooms, and fixing anything broken help all three buyer groups. A partial kitchen remodel usually does not, because renovators discount it and investors ignore it.
Frequently Asked Questions
Will calling it a fixer-upper get me lower offers?
Often, yes. The term invites buyers to subtract repair costs and profit, even when the house mainly needs cosmetic work.
It fits when real repairs are due, like a failing roof or furnace. Then the label sets honest expectations.
Do I still disclose problems if I sell as-is?
Yes. As-is changes what you agree to fix, not what you share. Colorado brokers use the Commission-approved Seller’s Property Disclosure and contract forms, and buyers keep their inspection rights.
Clear disclosure protects your price, because buyers who learn about an issue late tend to renegotiate harder.
Should I just take an investor’s cash offer?
Sometimes. Speed and certainty have real value if you are relocating or managing an estate.
Compare that offer with a list price built on original-condition sales. Todd’s take on selling your house to an investor covers how to test whether the gap is worth it.
Should I at least replace the old carpet?
Stained or pet-damaged carpet hurts photos and showings, while clean, dated carpet mostly becomes a credit buyers ask for.
Weigh the options in replacing carpet before selling against your timeline.
Will an original-condition home take longer to sell?
Not if the price matches the right comps.
Homes priced against updated sales are the ones that linger and then take reductions.
Selling a Dated Home in Windsor, CO: Which Label Fits Yours?
The tension is real. Updating costs money now and may not come back, while the wrong label can cost more at the closing table. Sellers usually lose money by overspending or by underselling a sound house.
Todd can help you sort out which condition label fits, which buyer pool it reaches, and how your home compares with original and updated sales nearby. When a question turns on a lender’s renovation-loan rules or the health of a system, he can help you frame it for the right lender or inspector.
That review rests on evidence: recent original-condition sales, active competition, showing activity on similar listings, and real update costs. Sometimes the honest answer is to leave the kitchen alone and price around it. You can start with a current value for your Windsor home.
Todd can show you what your comps say about selling a dated home in Windsor, CO as a fixer-upper or move-in ready. Call or text 970-286-5390.